Emergency Medical Evacuation Insurance: What Digital Nomads Need to Know
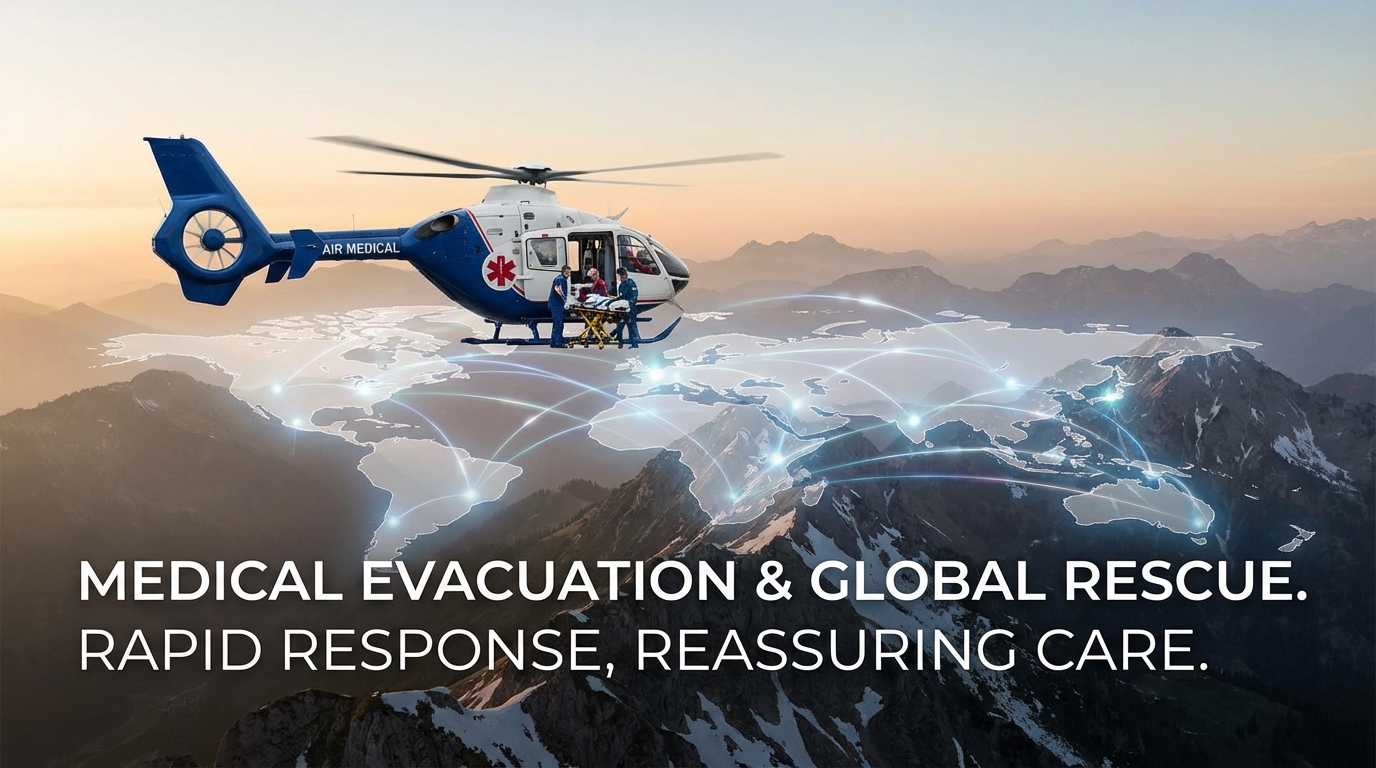
You're on a remote Indonesian island when a diving accident causes decompression sickness. The nearest hyperbaric chamber is in Bali—a helicopter flight away. Or worse: you have a heart attack in rural Thailand, and the local hospital can stabilize but not properly treat you.
These scenarios require emergency medical evacuation—transportation to a facility capable of providing appropriate care. Without insurance, evacuation can cost $50,000 to $250,000 or more. With proper coverage, you're protected.
This article is part of our complete digital nomad travel insurance guide.
What Emergency Evacuation Actually Covers
Medical Evacuation vs. Repatriation
These terms are often confused:
| Term | Meaning | When It's Used |
|---|---|---|
| Medical Evacuation | Transportation to nearest adequate medical facility | When local care is insufficient |
| Medical Repatriation | Transportation back to home country for care | When ongoing treatment needed at home |
| Repatriation of Remains | Transportation of body home after death | In event of death abroad |
What "Adequate Medical Facility" Means
Evacuation coverage typically transports you to the nearest facility capable of treating your condition—not necessarily your preferred hospital or home country.
Example: A cardiac emergency in rural Vietnam might result in evacuation to Ho Chi Minh City or Bangkok, not to your home country.
Implication: Evacuation home only happens when no closer adequate facility exists, or after initial stabilization when ongoing home-country care is deemed necessary.
Real Evacuation Cost Scenarios
Scenario 1: Diving Emergency in Indonesia
Situation: Decompression sickness on Gili Islands Needed: Helicopter to Bali for hyperbaric treatment
| Component | Approximate Cost |
|---|---|
| Emergency helicopter charter | $8,000-15,000 |
| Medical escort | $2,000-5,000 |
| Hyperbaric treatment | $5,000-15,000 |
| Total | $15,000-35,000 |
Scenario 2: Serious Accident in Rural Thailand
Situation: Motorcycle accident requiring spinal surgery Needed: Air ambulance to Bangkok, possible further evacuation
| Component | Approximate Cost |
|---|---|
| Ground ambulance stabilization | $500-2,000 |
| Air ambulance to Bangkok | $15,000-30,000 |
| Specialist surgery | $20,000-50,000 |
| Possible home evacuation | $50,000-100,000 |
| Total | $85,000-180,000+ |
Scenario 3: Heart Attack in Ecuador
Situation: Cardiac event at altitude requiring specialized care Needed: Medical flight to US for cardiac surgery
| Component | Approximate Cost |
|---|---|
| Local stabilization | $5,000-10,000 |
| Medical escort on commercial flight | $15,000-25,000 |
| OR Air ambulance to US | $75,000-150,000 |
| Total | $95,000-185,000 |
Scenario 4: Remote Hiking Accident in Nepal
Situation: Fall while trekking, broken pelvis at high altitude Needed: Helicopter rescue, evacuation from country
| Component | Approximate Cost |
|---|---|
| Helicopter rescue from remote area | $10,000-25,000 |
| Kathmandu hospitalization | $5,000-15,000 |
| Air ambulance out of country | $50,000-100,000 |
| Total | $65,000-140,000 |
Coverage Limits Comparison
By Provider
| Provider | Evacuation Limit | Repatriation Included |
|---|---|---|
| SafetyWing | $100,000 | Yes |
| World Nomads Standard | $300,000 | Yes |
| World Nomads Explorer | $500,000 | Yes |
| Insured Nomads Essentials | $250,000 | Yes |
| Insured Nomads Global | $1,000,000 | Yes |
| IMG Global Patriot | Up to $500,000 | Yes |
Why Limits Matter
| Limit | Adequate For |
|---|---|
| $100,000 | Most single-country evacuations in Asia, Latin America |
| $250,000 | Complex evacuations, most scenarios |
| $500,000+ | Long-distance air ambulance, remote areas, worst cases |
| $1,000,000+ | Maximum peace of mind, any scenario |
Reality check: Most evacuations cost $15,000-100,000. The $100,000 limit from SafetyWing covers the majority of scenarios—but leaves you exposed in worst cases.
Types of Evacuation Transport
Ground Ambulance
Used when: Adequate facility is reachable by road
Cost range: $500-5,000 depending on distance and country
Coverage: Almost always covered, rarely a coverage issue
Commercial Flight with Medical Escort
Used when: Patient is stable enough to fly commercial, but needs medical supervision
Cost range: $15,000-40,000 (business/first class seats plus medical escort)
Includes:
- Stretcher accommodation (often 6-9 economy seats)
- Licensed medical escort (nurse or paramedic)
- Medical equipment
- Airline coordination
Air Ambulance (Medical Jet)
Used when: Patient requires constant medical care during transport, or commercial travel isn't possible
Cost range: $50,000-250,000+
Factors affecting cost:
- Distance (fuel, crew time)
- Patient condition (equipment needed)
- Origin/destination airport fees
- Medical team requirements
Helicopter Evacuation
Used when: Patient needs extraction from remote location to hospital or airport
Cost range: $8,000-35,000
Common scenarios:
- Mountain rescue
- Island evacuation
- Remote accident sites
- Areas without roads
What Evacuation Coverage Does NOT Include
Political/Security Evacuation
Most medical evacuation coverage excludes:
- Evacuation due to political instability
- War zone extraction
- Civil unrest evacuation
- Natural disaster evacuation (unless injured)
Exception: World Nomads Explorer includes political evacuation.
Alternative: Separate security evacuation coverage from providers like Global Rescue or GEOS.
Search and Rescue
If you're lost or missing:
- Search operations are typically NOT covered
- Rescue after location may or may not be covered
- Depends on policy language
Non-Medical Emergencies
Not covered:
- Wanting to go home because you're unhappy
- Family emergency evacuation (to get YOU home)
- Fear-based evacuation (e.g., disease outbreak concerns)
Your Preferences
You cannot demand:
- Evacuation to a specific hospital
- Evacuation to your home country if closer facilities exist
- Upgrade to air ambulance when commercial is medically appropriate
The insurance company's medical team decides what's "medically necessary."
Standalone Evacuation Coverage
Some travelers add dedicated evacuation insurance for additional protection:
GEOS Travel Safety
Focus: Search and rescue + evacuation Cost: ~$200-300/year Coverage: Up to $500,000 evacuation, includes SAR
Best for: Adventure travelers, remote destinations, hikers/climbers
Global Rescue
Focus: Premium evacuation and security services Cost: ~$300-500/year Coverage: Evacuation to home hospital, not just nearest facility
Best for: Those wanting evacuation HOME, not just to adequate care
MedjetAssist
Focus: Air ambulance membership Cost: ~$300-400/year Coverage: Air ambulance to home hospital of choice
Best for: Those prioritizing hospital choice and home-country care
When Standalone Makes Sense
Consider standalone evacuation if:
- Your travel insurance has low evacuation limits ($100,000)
- You travel to remote areas regularly
- You pursue high-risk activities
- You want evacuation to home hospital, not nearest adequate facility
How Evacuation Actually Works
Step 1: Incident Occurs
You experience a medical emergency that local facilities cannot adequately treat.
Step 2: Contact Assistance Line
Call your insurance company's 24/7 emergency assistance line. They need to:
- Assess the situation
- Determine if evacuation is warranted
- Authorize the evacuation
Critical
Do NOT arrange your own evacuation without insurer approval. Unauthorized evacuations may not be reimbursed. Always contact your insurer first unless in immediate life-threatening danger.
Step 3: Medical Assessment
The insurer's medical team:
- Reviews your condition with local doctors
- Determines appropriate level of care
- Decides evacuation destination and method
Step 4: Coordination
The insurer coordinates:
- Transport arrangements (ambulance, aircraft)
- Medical escort if needed
- Receiving hospital
- Family notification
Step 5: Execution
You're transported to the appropriate facility. The insurer typically:
- Pays providers directly
- Handles logistics
- Manages paperwork
Step 6: Follow-Up
After stabilization:
- Further evacuation home if medically necessary
- Repatriation arrangements
- Claims processing for related expenses
Maximizing Your Evacuation Coverage
Before You Travel
- Know your coverage limits and whether they're adequate for your destinations
- Save emergency numbers in multiple locations (phone, cloud, wallet card)
- Understand the process before you need it
- Consider standalone coverage if traveling to remote areas
During an Emergency
- Contact your insurer first (unless immediate life-threatening)
- Get authorization before arranging transport
- Document everything (names, times, communications)
- Follow medical team guidance
Choosing Coverage
| If You Travel To... | Consider Minimum Evacuation |
|---|---|
| Major cities only | $100,000 |
| Mix of urban/rural | $250,000 |
| Remote areas regularly | $500,000+ |
| Extreme remote/adventure | $500,000+ plus standalone |
FAQ
Frequently Asked Questions
Related Guides
- Complete Digital Nomad Travel Insurance Guide
- SafetyWing vs World Nomads vs Insured Nomads
- Travel Insurance for Adventure Activities
- Travel Insurance by Region
- How to File a Travel Insurance Claim
- Medical Emergencies Abroad: Action Plan
- Complete Healthcare Guide for Digital Nomads
Emergency evacuation coverage is the feature you hope never to use but absolutely need when disaster strikes. The costs of uninsured evacuation can reach $100,000-250,000—potentially wiping out years of savings in a single incident.
Choose coverage limits appropriate for your destinations and activities. For remote travel or adventure activities, consider supplemental evacuation coverage. And always, always contact your insurer before arranging transport—unauthorized evacuations risk claim denial.
The peace of mind from proper evacuation coverage is worth far more than the premium.
About the Author