International Health Insurance vs Travel Insurance: Which Do Digital Nomads Need?
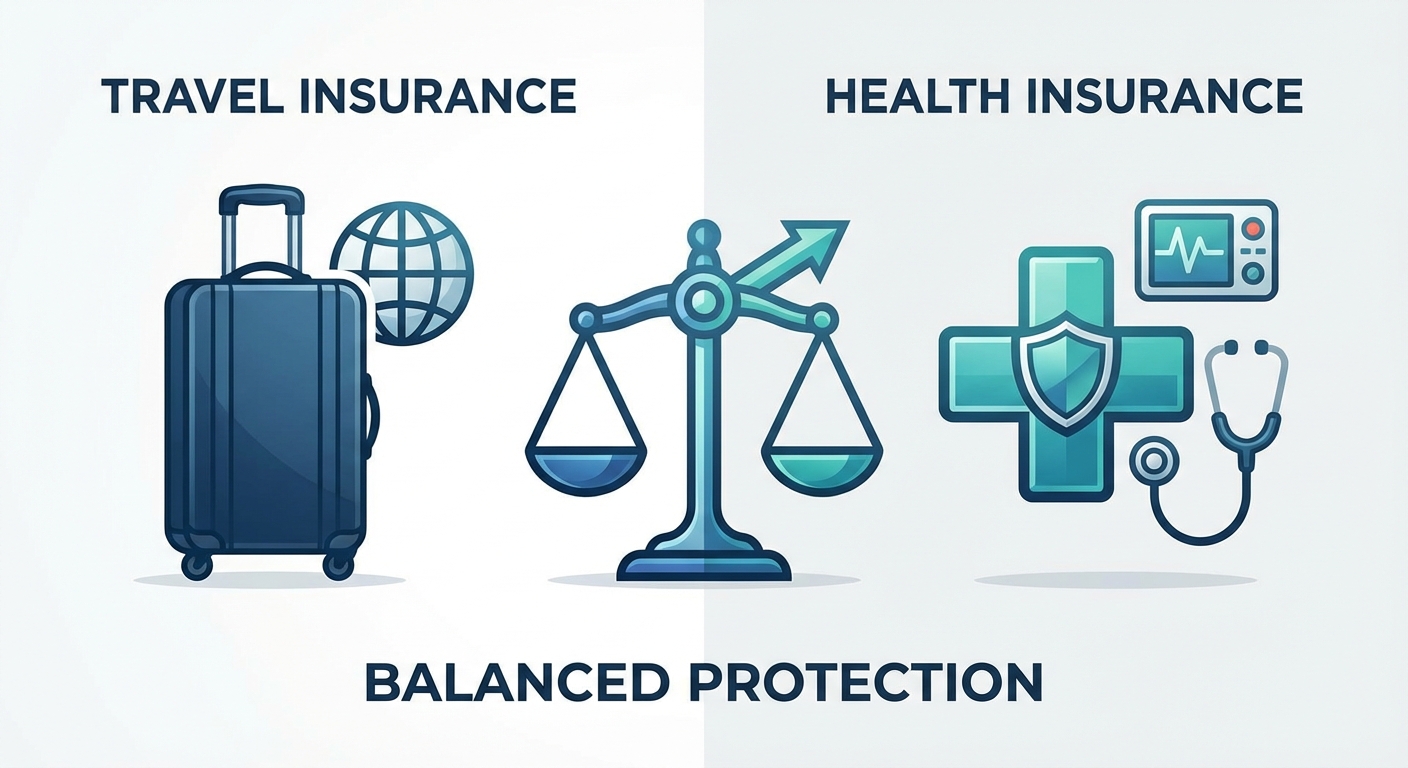
Travel insurance and international health insurance both protect you abroad—but they're fundamentally different products designed for different needs. Understanding the distinction helps you choose the right coverage for your nomad lifestyle.
Most nomads start with travel insurance. Some eventually upgrade to international health insurance. This guide explains when each makes sense.
This article is part of our complete digital nomad travel insurance guide.
The Fundamental Difference
Travel Insurance
Purpose: Protect against unexpected emergencies during travel
Designed for: Travelers who have a home base and healthcare access in their home country
Focus: Catastrophic events, trip disruptions, emergencies
Coverage: Emergency medical, evacuation, trip cancellation, gear
Typical cost: $50-200/month
International Health Insurance (IPMI)
Purpose: Comprehensive healthcare coverage worldwide, similar to domestic health insurance
Designed for: Expats, long-term travelers, people without home country healthcare
Focus: Complete healthcare including routine care, preventive services, ongoing treatment
Coverage: Everything from checkups to major surgery
Typical cost: $200-500+/month
Coverage Comparison
| Feature | Travel Insurance | International Health Insurance |
|---|---|---|
| Emergency medical | Yes | Yes |
| Emergency evacuation | Yes | Yes |
| Routine doctor visits | No | Yes |
| Preventive care | No | Yes |
| Prescriptions (ongoing) | No | Yes |
| Dental (routine) | No | Often included |
| Vision | No | Often included |
| Mental health (ongoing) | Rarely | Usually |
| Pre-existing conditions | Excluded | Can be covered |
| Chronic condition management | No | Yes |
| Direct billing network | Limited | Extensive |
| Trip cancellation | Yes | No |
| Gear coverage | Yes | No |
Cost Comparison
Travel Insurance (Age 30, Single)
| Provider | Monthly Cost | Medical Maximum |
|---|---|---|
| SafetyWing | $48 | $250,000 |
| World Nomads | $100-140 | $100,000-300,000 |
| Insured Nomads | $140-200 | $500,000-1,000,000 |
International Health Insurance (Age 30, Single)
| Provider | Monthly Cost | Medical Maximum |
|---|---|---|
| Cigna Global (Silver) | $200-300 | $1,000,000 |
| Cigna Global (Gold) | $300-400 | $2,000,000 |
| Allianz Worldwide | $250-350 | $1,000,000+ |
| IMG Global (Premium) | $200-300 | Varies |
| BUPA Global | $300-450 | $3,000,000+ |
The cost gap: International health insurance costs 2-4x more than travel insurance.
When Travel Insurance Is Sufficient
Travel insurance works well when you:
Are Young and Healthy
- No chronic conditions requiring ongoing care
- No regular medications
- No pre-existing conditions
Don't Need Routine Care
- Can wait until home visits for checkups
- No ongoing treatment requirements
- Comfortable with emergency-only coverage
Have Home Country Healthcare
- Maintain health insurance or NHS access at home
- Can return home for non-emergency care
- Regular home visits for medical needs
Are Starting Out
- Testing the nomad lifestyle
- Uncertain about long-term plans
- Budget-conscious
Maintain a Home Base
- Spend significant time in home country
- Use home healthcare for most needs
- Travel is intermittent, not continuous
When International Health Insurance Makes Sense
Upgrade to IPMI when:
You Have Health Needs
- Chronic conditions requiring ongoing care (diabetes, heart disease, etc.)
- Regular medications that need monitoring
- Pre-existing conditions you need covered
- Mental health treatment needs
For more on this, see our pre-existing conditions guide.
You've Fully Location-Decoupled
- No longer maintain home country healthcare
- No regular home country visits
- Permanently nomadic or expat lifestyle
- Home country healthcare access lost
You Want Comprehensive Care
- Regular checkups and preventive care
- Routine dental and vision
- Direct access to specialists
- Don't want to wait for emergencies
You're Over 40
- Higher probability of health issues
- More value from preventive care
- Pre-existing conditions more likely
- Premium gap between travel and IPMI narrows with age
You're Settling Into One Country
- Long-term stay (6+ months)
- Establishing relationships with doctors
- Want consistent ongoing care
- Building health infrastructure abroad
The "Slow Nomad" Gray Area
Many digital nomads exist between tourist and expat:
- Traveling continuously but not settling
- No home country healthcare but not expat either
- Healthy now but uncertain about the future
Options for Gray Area Nomads
Option 1: Premium Travel Insurance
Insured Nomads or similar with:
- Higher coverage limits
- Telehealth access
- Some routine care coverage
Cost: $150-250/month
Option 2: Travel Insurance + Local Healthcare
Combine travel insurance for catastrophic events with:
- Paying out-of-pocket for routine care (cheap in many countries)
- Local health insurance in long-stay countries
Cost: $50-100/month insurance + variable out-of-pocket
Option 3: Budget International Health Insurance
Entry-level IPMI with higher deductibles:
- Cigna Global with high deductible
- IMG Global entry tiers
Cost: $200-300/month with $2,000-5,000 deductible
Provider Deep Dive
Cigna Global
Best for: Comprehensive worldwide coverage
- Multiple plan tiers (Silver, Gold, Platinum)
- Large provider network
- Telehealth included
- Pre-existing condition coverage available
- Mental health coverage
- Direct billing in most situations
Starting cost: ~$200/month (30-year-old, Silver tier)
Allianz Worldwide Care
Best for: Strong European coverage
- Multiple plan options
- Excellent European network
- Good for EU-based nomads
- Pre-existing condition options
Starting cost: ~$250/month (varies by plan)
IMG Global (PatriotExchange)
Best for: Flexible, customizable coverage
- Choose coverage levels
- Choose deductible
- Good bridge between travel and full IPMI
- More affordable entry points
Starting cost: ~$200/month (varies significantly by options)
BUPA Global
Best for: Premium comprehensive coverage
- Top-tier coverage
- Extensive network
- Full preventive care
- Mental health included
- Premium pricing
Starting cost: ~$350/month
SafetyWing Remote Health
Best for: Nomads upgrading from travel insurance
- Designed specifically for remote workers
- Easier transition from Nomad Insurance
- More affordable than traditional IPMI
- Limited network compared to major IPMIs
Starting cost: ~$180/month
Making the Transition
When to Upgrade
Consider transitioning to IPMI when:
- Health needs change (new diagnosis, aging)
- Travel becomes truly permanent
- Budget allows premium coverage
- Peace of mind worth the cost
- Home country healthcare no longer accessible
How to Transition
- Research options during current coverage period
- Apply for IPMI while still covered by travel insurance
- Complete medical underwriting (may take 2-4 weeks)
- Overlap coverage briefly to prevent gaps
- Cancel travel insurance after IPMI begins
Potential Complications
- Pre-existing conditions may be excluded initially
- Waiting periods for some coverage
- Medical underwriting may affect pricing
- Some conditions may be uninsurable
Hybrid Approaches
Travel Insurance + Out-of-Pocket Routine Care
How it works:
- Travel insurance for emergencies ($50-150/month)
- Pay cash for routine care (often cheap abroad)
Best for: Healthy nomads in affordable healthcare regions
Example budget:
- SafetyWing: $48/month
- Occasional doctor visit: $30-50
- Annual checkup: $100-200
- Total: ~$75-100/month
Travel Insurance + Country-Specific Insurance
How it works:
- Travel insurance for global coverage
- Local health insurance for country of primary residence
Best for: Base + travel nomads, digital nomad visa holders
Example:
- SafetyWing: $48/month
- Thai Social Security (if working legally): ~$30/month
- Total: ~$80/month with robust local coverage
Premium Travel Insurance as Bridge
How it works:
- Use premium travel insurance with IPMI-like features
- Insured Nomads Global Medical or similar
Best for: Those needing more than budget travel insurance but not ready for full IPMI
Cost: $150-250/month
FAQ
Frequently Asked Questions
Decision Framework
Choose Travel Insurance If:
- Under 40 and healthy
- No pre-existing conditions
- No ongoing care needs
- Have home country healthcare access
- Budget is priority
- Testing nomad lifestyle
Choose International Health Insurance If:
- Have chronic conditions or pre-existing health issues
- Need ongoing care or regular medications
- No home country healthcare access
- Over 40 (especially over 50)
- Want preventive care and routine coverage
- Committed to long-term nomadism
- Peace of mind worth the premium
Consider Hybrid Approach If:
- In the gray area between healthy and health needs
- Want more than budget insurance, less than full IPMI
- Have specific local coverage options
- Budget-conscious but want better coverage
Related Guides
- Complete Digital Nomad Travel Insurance Guide
- Travel Insurance for Pre-Existing Conditions
- Best Long-Term Travel Insurance (6+ Months)
- SafetyWing vs World Nomads vs Insured Nomads
The choice between travel insurance and international health insurance isn't binary. Start with travel insurance when you begin nomading. Reassess as your situation evolves. Upgrade to IPMI when your health needs, commitment level, or peace of mind requirements justify the premium.
Most nomads spend years with travel insurance before considering IPMI. Some never need to upgrade. Understanding both options lets you make the right choice for your specific situation.
About the Author